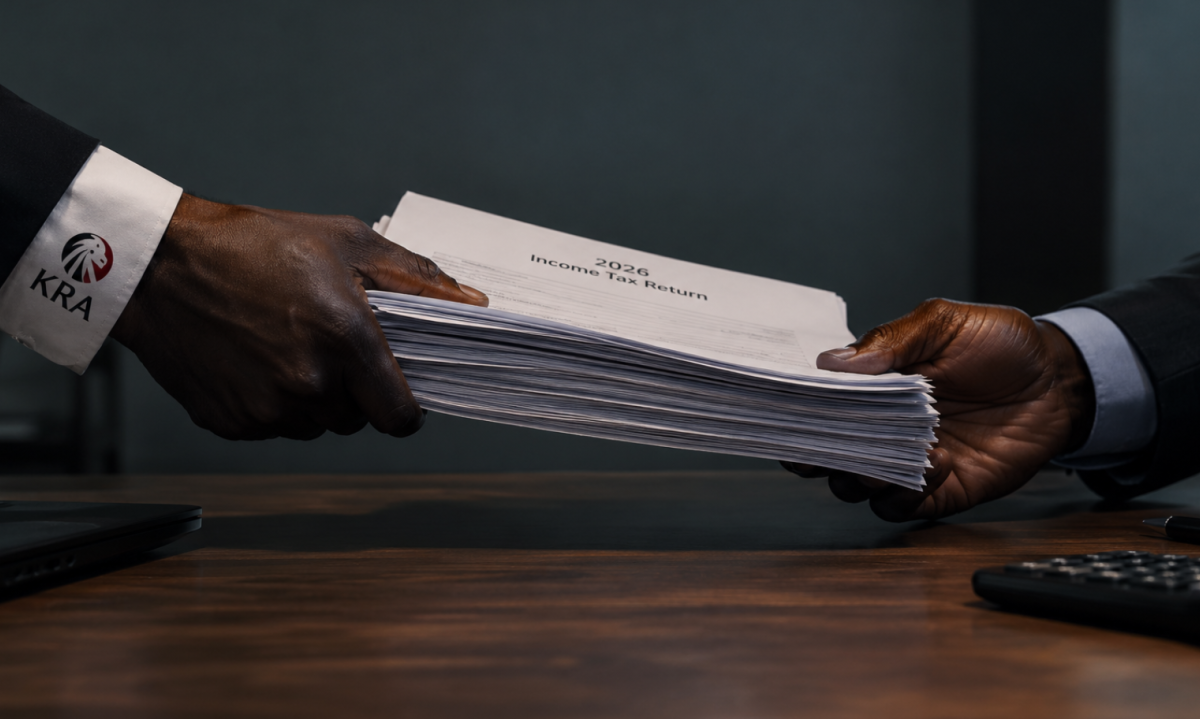
It is the last week of January 2027. An iTax notice lands in your inbox stating that your company’s income tax return for 2026 is ready. Your finance team had no hand in preparing it; the Kenya Revenue Authority built the file itself.
The sales line reads KSh 200m, matching your general ledger to the shilling. Below it, the expenses line reads KSh 140m, which is the exact sum your suppliers invoiced through eTIMS against your company PIN during the year. Your own ledger shows KSh 170m in expenses. On KRA’s numbers, the business made KSh 60m in taxable profit and owes KSh 18m in corporation tax. On your books, taxable profit sits at KSh 30m with a KSh 9m tax bill.
You now have two months to account for KSh 30m in costs that KRA’s servers cannot see. Which documents will you send?
The case.
No bench at the Tax Appeals Tribunal has heard this dispute yet because the statute creating it is only four months old. President William Ruto assented to the Finance Act 2026 on 23 June 2026, and section 47 inserted six new subsections into section 75 of the Tax Procedures Act with effect from 1 July 2026. Where iTax previously pre-populated only P9 employment income for salaried staff, the new provisions empower the Commissioner to generate a pre-populated return from KRA’s systems for any taxpayer required to lodge a return, notify the taxpayer once it is issued, and issue it on or before the end of January. A taxpayer who receives one may rely on those pre-filled numbers to file, and the statute directs that the taxpayer “shall confirm or amend the pre-populated return within two months” of issue

Alongside pre-filled returns, section 44 of the Finance Act inserted a new section 29A into the Tax Procedures Act, empowering the Commissioner to raise a tax assessment directly from records KRA already holds on file. That pool of data spans PAYE filings and withholding tax schedules, eTIMS electronic invoices under section 23A, internal data-management logs under section 59A, customs and inspection records, prior audit findings, and statutory filings lodged under any other written law. Before issuing that assessment, the Commissioner may write to request supporting records, giving the taxpayer at least 30 days to respond.
KRA’s public notice of November 2025 (effective 1 January 2026) established the validation sources a full year ago, informing taxpayers that 2025 income and expense declarations would be cross-checked against TIMS/eTIMS records, withholding income tax gross schedules, and customs import entries. A follow-up notice on 8 June 2026 offered 2025 filers one final grace period: expenses lacking eTIMS invoices could still be declared on the 2025 return, subject to post-filing validation. That window closed with the 2025 tax year. Starting with the 2026 year of income, KRA’s June notice stated that all declared revenue and deductible costs must rest on valid electronic tax invoices. Indeed, since January 2024, the Income Tax Act and Section 23A of the Tax Procedures Act have barred tax deductions for unsupported expenses, carving out narrow statutory exceptions such as emoluments, customs imports, financing interest, and airline passenger ticketing.
Statutory filing deadlines are shifting forward as well. Under sections 1(a), 17, and 18 of the Finance Act 2026—which take effect on 1 January 2027—individual taxpayers must furnish their annual returns and self-assessments within four months of the close of their year of income rather than six, bringing the 2026 filing deadline forward to 30 April 2027. Corporate taxpayers retain their six-month window under section 52B(1)(b), meaning a company with a 31 December year-end must file by 30 June 2027.
In August 2026, KRA noted that further operational guidance would clarify how pre-populated returns will be rolled out and which taxpayer cohorts will receive them first. Meanwhile, the statute itself leaves a conspicuous gap around what happens when a taxpayer who is issued a pre-populated return neither confirms nor amends it inside the two-month statutory window. Subsidiary regulations by the Cabinet Secretary under the newly inserted section 112(2)(ba) are meant to prescribe the exact filing procedure, though none had been gazetted by 22 October 2026.

The precedents.
While no tribunal panel has ruled on a section 75 pre-populated return yet, the Tribunal has adjudicated dozens of disputes built on the exact same tension, where KRA’s third-party data says one thing and a company’s general ledger says another. We have read several of those rulings across this course.
In our Precursor Executive Classroom Lecture 24, withholding tax certificates lodged by a customer alerted KRA that Kinya was making substantial taxable supplies, triggering a KSh 26.4m VAT demand. In Lecture 20, Harley Berry submitted nil VAT returns even as withholding VAT credits accumulated against its PIN; the company lost KSh 317.9m at the Tribunal after failing to produce the tax invoices mandated by the VAT Act. In Lecture 25, KRM Commodities failed to reconcile a KSh 184.6m variance between its 2023 purchase ledger and KRA’s customs import database, and a bundle of unindexed email attachments fell well short of discharging the evidentiary burden under section 30 of the Tax Appeals Tribunal Act.
By contrast, in Lecture 23, Jilk Construction prevailed wherever its paper trail was complete. Backed by signed correspondence and contemporaneous ledger extracts, the contractor struck out more than KSh 1.3bn in disputed assessments. On the line items where Jilk produced bare invoices and summary schedules without underlying proof, the challenge failed, and the Tribunal laid down a principle worth remembering: a taxpayer cannot claim the tax credit on a withholding certificate while simultaneously disputing the revenue shown on that same certificate. Finally, in Lecture 50, Cedar Marketing lodged its appeal nearly three years out of time, meaning the Tribunal dismissed the case at the door without ever opening a single invoice.
Across all five rulings, KRA’s third-party databases set the opening number, and the taxpayer only reduced the bill to the extent that contemporaneous documents proved otherwise within the statutory timeline. From 2027, wherever KRA issues a pre-populated return, that sequence moves to the very start of the filing season. KRA’s calculation can arrive in January, months before the final return is due and years before a traditional field audit would ever begin.
A finance director who receives a pre-populated return and lets the two-month confirmation window expire in silence will find that while section 75 says nothing about penalties, the rest of the Tax Procedures Act is fully armed. The underlying annual return remains due on schedule. KRA’s June 2026 notice reminded taxpayers that non-filers face default assessments under section 29, while the new section 29A lets the Commissioner raise an assessment straight from KRA’s internal databases. Filing a corporate return late triggers a penalty of 5 per cent of the tax payable or KSh 20,000, whichever is higher; for an individual, the floor is 5 per cent or KSh 2,000. Paying late adds another 5 per cent penalty alongside interest compounding at 1 per cent per month. Once an assessment is issued, section 30 places the entire legal burden of disproving it on the taxpayer.
The idea: the writing on the wall.
In the fifth chapter of the Book of Daniel, King Belshazzar of Babylon throws a great banquet for a thousand of his nobles, drinking wine from the golden temple vessels carried off from Jerusalem. Mid-banquet, the fingers of a human hand appear and inscribe four Aramaic words into the plaster of the palace wall. None of the royal astrologers can decipher the script, so Daniel is summoned to read it aloud. Mene: God has numbered the days of your reign and brought it to an end. Tekel: you have been weighed on the scales and found wanting. Peres: your kingdom is divided and handed over to the Medes and Persians. Before dawn, Belshazzar is dead.
Belshazzar’s fatal miscalculation happened long before the banquet began. An unseen auditor had already tallied his reign, and the king only discovered the score once it was carved into the plaster in front of his guests.
In a landmark 2000 paper, economists Brigitte Madrian and Dennis Shea tracked a large US corporation that switched its 401(k) retirement scheme to automatic enrolment for newly hired staff. Plan participation jumped immediately. Crucially, a vast majority of those new hires stayed parked at the company’s default contribution rate and inside the default money-market fund, an allocation almost none of the earlier cohorts had picked when forced to make an active choice. The underlying investment menu had stayed identical, yet changing the zero-effort option reshaped how thousands of people behaved.
A pre-populated tax return turns KRA’s internal calculation into the zero-effort default. Accepting the Commissioner’s number takes a click on iTax. Amending it requires pulling source vouchers, building line-by-line reconciliations, and freeing up a finance team in February and March. Behavioural inertia alone guarantees that many taxpayers who receive a pre-filled return will end up settling their tax bills on KRA’s opening figures.
For most of the history of modern income tax, the business owner held an informational edge over the revenue authority. Today that asymmetry has shifted. Through eTIMS logs, PAYE filings, withholding schedules, and customs declarations, KRA already holds the counterparty record for nearly every shilling moving through a formal business, leaving the taxpayer as the sole custodian of whatever adjustments sit solely inside the private ledger.
What a better-run business will do before 31 December.
A disciplined finance team runs KRA’s internal cross-check before the tax year closes. Following the advice KRA itself published in its November 2025 notice, the chief financial officer requests the company’s TIMS/eTIMS output and input schedules directly from its designated KRA account manager and reconciles them month by month against the general ledger. Every variance between the trial balance and KRA’s records on outward sales, inward PIN-tagged purchases, customs entries, or withholding certificates is either corrected at the source or documented in a contemporaneous working file.
Chasing non-compliant vendors happens in November rather than March. Any local expense lacking an eTIMS invoice tagged to the buyer’s PIN is a tax deduction at risk of disallowance. For a profitable company paying corporation tax at 30 per cent, a KSh 1m supply backed by a valid eTIMS invoice has a net after-tax cost of KSh 700,000; without that electronic invoice, the net cost jumps to the full KSh 1m. Vendors who refuse to issue eTIMS invoices are either repriced to absorb that 30 per cent tax leakage or dropped from the supplier master file before year-end.
Every withholding tax certificate lodged by a customer must also be tied back to recognised revenue. Because KRA’s validation and pre-population engines treat withholding certificates as confirmed gross income, any erroneous certificate filed by a client must be cancelled or amended through iTax before 31 December. Where the certificate is accurate, the matching revenue belongs in the 2026 books. As Jilk Construction demonstrated, claiming the withholding tax credit while denying the underlying turnover is a losing argument at the Tribunal.
Legacy tax arrears should also be cleared before the statutory amnesty window shuts. Under section 37E of the Tax Procedures Act (as amended by section 45 of the Finance Act 2026), penalties and interest on unpaid principal tax for periods up to 31 December 2025 are waived in full provided the principal tax is paid by 31 December 2026.
Finally, a prudent board assigns a single named executive to watch for the January iTax notice. Where KRA issues a pre-populated return, that officer opens it the week it arrives, sets it beside the closed 2026 trial balance, and prepares the amendment package well inside the two-month statutory limit. Whenever iTax malfunctions or rejects an upload, that same officer logs time-stamped screenshots and KRA support tickets—evidence the Commissioner is now empowered to weigh under section 89(5B) when waiving up to KSh 2m in penalties and interest caused by errors generated by an electronic tax system.
Lessons for the boardroom.
- KRA can now speak first. From January 2027, the Commissioner’s figure—built from eTIMS, withholding schedules, PAYE, and customs entries—can reach you on iTax before your own return does.
- The confirmation window is two months. Where KRA issues a pre-populated return by 31 January, the taxpayer has two months from the date of issue to confirm or amend it, ahead of the 30 April filing deadline for individuals and 30 June for December year-end companies.
- Your supporting paper must exist by 31 December. An amendment or return validation in early 2027 can only rely on valid eTIMS invoices and statutory records generated during the 2026 tax year.
- A missing eTIMS invoice carries a 30 per cent cost. For a profitable company, losing the tax deduction on an unsupported purchase forfeits corporation tax relief on the full invoice price.
- Silence is a losing strategy. While section 75 does not state what follows an ignored pre-populated return, section 29 default assessments, section 29A data assessments, late-filing penalties, and the statutory burden of proof fill the gap immediately.
Belshazzar only read the handwriting on the plaster after the numbering of his kingdom was finished. By 31 January 2027 the Commissioner’s hand can write on iTax, and the ledgers your business will be weighed against close on 31 December 2026.

In January 2027, KRA may send your company a tax return it has already filled in.
The figures will come from eTIMS invoices, withholding certificates, PAYE and customs records. You will then have two months to confirm them or prove them wrong. From the 2026 year of income, every shilling of income and expense you declare must rest on a valid eTIMS invoice. The year closes in 70 days.
FINTAK members will meet changes like this early, with the source, the deadline and the questions their teams should be asking. From 2027, every member receives a monthly regulatory brief that separates proposals from rules already in force, alerts when a verified deadline is near, and four expert clinics a year built on members’ own questions, from tax documentation to data protection. The brief goes to members only.
Membership that earns its renewal. Three tiers, from KES 50,000 to KES 250,000 a year.
Join before 30 November 2026 and pay the full fee for two years of membership, or half the fee for one year.
Apply at https://www.fintechassociation.africa/membership or write to admin@fintechassociation.africa