
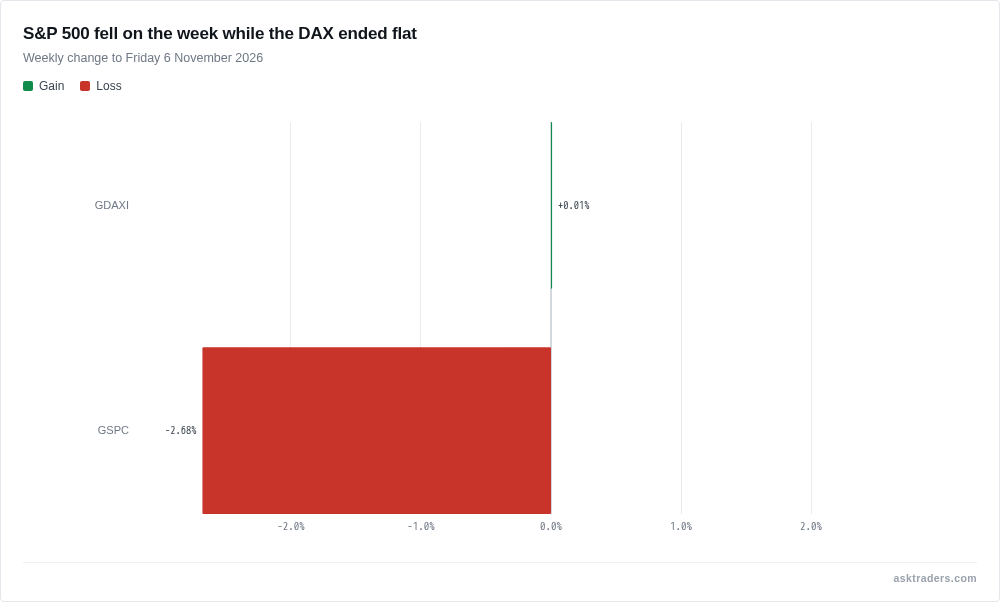
US October consumer price inflation and UK third-quarter GDP are the two data releases that matter most this week. They follow a heavy week for US shares: the S&P 500 closed on Friday at 7,376.86, down 2.68% on the week, including a fall of about 4.4% on Thursday. Cisco and Applied Materials report on Thursday after the US close. No Fed, ECB or BoE rate decision is scheduled.
The DAX, Germany’s blue-chip index, ended the week at 25,820.36, up 0.01%, after falling 1.92% on Friday. All times are UK time.
Monday
- 01:30 China: CPI, October. Consensus 0.8% y/y, previous 0.9%.
- 07:00 Germany: trade balance, September. Consensus 19.4, previous 19.5.
- 09:30 Eurozone: Sentix, November. Consensus 2.1, previous 2.7.
- 13:40 US: Fed’s Bowman speaks. No consensus.
- 15:00 US: Fed’s Goolsbee speaks. No consensus.
- 16:00 US: consumer inflation expectation, October. Consensus 3.8%, previous 3.9%.
- 17:30 UK: BoE’s Bailey speaks. No consensus.
Tuesday
- 03:00 China: trade balance, October. Consensus 126.5, previous 133.53.
- 12:30 UK: BoE’s Lombardelli speaks. No consensus.
- 13:30 US: CPI, October. Consensus 0.3% m/m, previous 0.6%; consensus 3.7% y/y, previous 3.7%. Core CPI: consensus 0.2% m/m, previous 0.3%; consensus 2.5% y/y, previous 2.6%.
- 14:35 US: Fed’s Logan speaks. No consensus.
- 18:30 UK: BoE’s Pill speaks. No consensus.
Wednesday
- 08:20 Germany: Bundesbank’s Nagel speaks. No consensus.
- 09:45 Eurozone: ECB’s Lagarde speaks. No consensus.
Thursday
- 07:00 UK: GDP, third quarter. Consensus 0.7% q/q, previous 0.5%; consensus 1.7% y/y, previous 1.4%. September: consensus 0.0% m/m, previous 0.1%; consensus 1.9% y/y, previous 2.1%.
- 07:00 UK: industrial production, September. Consensus -0.4% m/m, previous 0.8%. Manufacturing production: consensus -0.5% m/m, previous 1.2%.
- 13:30 US: initial jobless claims, week to the 7th of November. Consensus 195,000, previous 189,000.
- 15:00 US: existing home sales, October. Consensus 3.98, previous 3.99.
- 19:30 Eurozone: ECB’s Lagarde speaks. No consensus.
- 21:30 Eurozone: ECB’s Lagarde speaks. No consensus.
- 23:30 US: Fed’s Williams speaks. No consensus.
Friday
- 10:00 Eurozone: employment, third quarter. Consensus 0.2% q/q, previous 0.1%.
- 13:30 US: producer price index (PPI). No consensus.
- 14:10 US: Fed’s Collins speaks. No consensus.
- 15:50 US: Fed’s Bowman speaks. No consensus.
The two that matter most
US CPI is the first. The calendar’s consensus is a 0.3% monthly rise against 0.6% previously, and 3.7% on the year, unchanged. Core CPI is expected at 0.2% on the month and 2.5% on the year, against 0.3% and 2.6% previously. The Fed’s target range stands at 3.75% to 4.00%, and several Fed speakers are scheduled across the week.
UK GDP is the second. Third-quarter growth is expected at 0.7% on the quarter, against 0.5% previously, and 1.7% on the year, against 1.4%. The figures arrive at 07:00 on Thursday.
Earnings
Consensus EPS (earnings per share): Monday after the US close: Take-Two 0.49. Tuesday before the open: Sea Ltd 0.79, On Holding 0.42. Wednesday after market: RWE 0.66. Thursday after market: Allianz 7.51, Siemens 2.81. Thursday after the US close: Cisco 1.15, Applied Materials 4.06, Nu Holdings 0.22.
Where rates stand going in
The Fed’s target range is 3.75% to 4.00%. The ECB’s deposit rate is 2.5%. No Fed, ECB or BoE rate decision is scheduled this week, so the speeches from Bowman, Lagarde, Bailey and others are the central bank events.